
Moving abroad can change where you pay tax, how much you owe and what happens to income you still receive from the UK. The good news? Understanding the rules before you leave can help you plan your move and make the most of your money.
You’ve found somewhere you’d love to live, started looking at properties and perhaps even pictured your first morning in your new home. But before you pack up your life in Britain, there’s one practical question worth answering: what happens to your taxes when you move abroad?
The answer depends on where you’re going, how long you’ll spend there and what income or assets you have in the UK. Here’s what you need to know about the taxes that could affect your move.
What happens to your taxes when you move abroad? If you move overseas permanently, you may stop paying UK tax on most income earned abroad, but you could still owe UK tax on pensions, rental income or property sales. You may also become liable for taxes in your new country. Your tax residency status and any double taxation agreement between the two countries determine which rules apply.
Contents
- Will you still pay UK tax after moving abroad?
- Will you have to pay income tax in your new country?
- Can you end up paying tax in two countries?
- What happens to tax on your UK pension?
- Will you pay tax if you sell or rent out your UK home?
- What taxes will you pay when buying a property abroad?
- What happens to your savings, investments and inheritance tax?
- What if you decide to move back to the UK?
- What should you do before moving abroad?
- Summary
- Frequently asked questions
Thinking about moving or buying abroad? Start here
Spend one online day getting practical answers on property, visas, tax, finance and the next steps in your overseas plans.
- 35+ live seminars
- Speak to industry experts
- 30 days of on-demand access
Join at any point during the day.
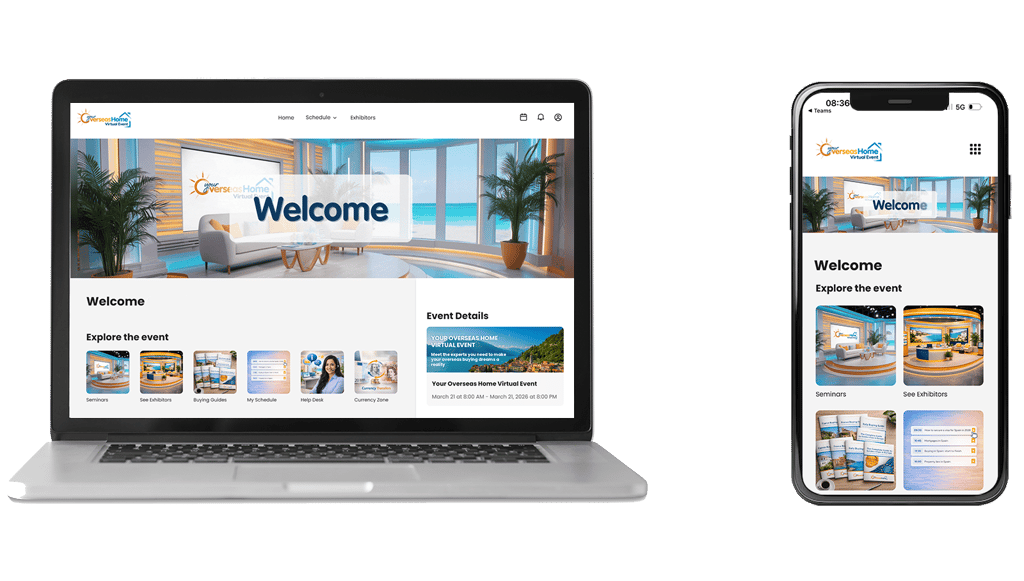
Get practical answers before you buy or move abroad
Explore upcoming expert-led sessions on property, finance, tax, legal issues, visas and relocation.
Will you still pay UK tax after moving abroad?
One of the first things to understand is tax residency. This determines which country has the right to tax different parts of your income.
In the UK, your tax residency is assessed using HMRC's Statutory Residence Test. It considers how much time you spend in Britain, whether you work here and what connections you maintain, such as a home or family.
You may have heard that spending fewer than 183 days in the UK means you're no longer a tax resident. It's not quite that simple.
Spending 183 days or more in the UK during a tax year generally makes you UK tax resident. However, spending fewer days here doesn't automatically make you non-resident. Depending on your circumstances, you could still qualify as a UK resident because of your connections to the country.
If you become non-UK resident, you'll generally stop paying UK tax on foreign income and gains. However, certain UK income and gains may remain taxable.
There may also be some flexibility in the year you leave. Under what's known as split-year treatment, you could be treated as UK resident for one part of the tax year and non-resident for the other, provided you meet the conditions.
What you can do
Before choosing your moving date, check your position using HMRC's guidance on UK tax residency. This is particularly important if you're keeping a home in Britain or expect to visit regularly.
Will you have to pay income tax in your new country?
Quite possibly. Once you become tax resident overseas, your new country may tax your worldwide income, including money you continue receiving from the UK.
The rules differ between destinations. Spain, France, Portugal, Italy, Greece and Cyprus each have their own tax residency requirements, income tax systems and reporting obligations.
For example, spending more than 183 days in Spain during a calendar year is one of the main ways you can become Spanish tax resident. However, your economic interests and family circumstances can also be relevant.
France has different tests, including where your main home, principal professional activity or centre of economic interests is located.
This is why it's worth looking into the local tax rules before you relocate, rather than assuming the same arrangements will apply everywhere.
What you can do
Speak to a tax adviser familiar with both the UK and your destination. They can explain when you might become tax resident and whether the timing of your move makes a difference.
Can you end up paying tax in two countries?
It's possible for two countries to consider you tax resident at the same time. You might also have income that both countries have the right to tax.
Fortunately, the UK has double taxation agreements with many countries, including Spain, France, Portugal, Italy, Greece and Cyprus.
These agreements establish how different types of income should be taxed and provide mechanisms for avoiding or reducing double taxation.
For example, imagine you've retired to Spain but still receive income from a property you rent out in the UK.
The UK may tax that rental income because the property is located there. Spain may also require you to declare it as part of your worldwide income. Depending on the circumstances, you may be able to claim relief for tax already paid.
However, a double taxation agreement doesn't necessarily mean you'll pay the lower of the two countries' tax rates. You may still have additional tax to pay, and claiming relief can involve paperwork.
What you can do
Check the UK's double taxation agreements and find out which income you'll need to declare in each country.
What happens to tax on your UK pension?
If you're retiring overseas, your pension will probably be one of your main sources of income, so understanding how it's taxed is particularly important.
You can generally continue receiving your UK State Pension abroad, but where you pay tax on it depends on your residency status and the relevant tax treaty.
Private and workplace pensions can be treated differently. Some may be taxable in your new country of residence, while certain government-service pensions are generally taxed in the UK, subject to treaty provisions and exceptions.
It's also worth checking how any pension lump sums will be taxed before withdrawing them. A payment that benefits from favourable tax treatment in the UK may be treated differently overseas.
For example, someone retiring to France with a UK State Pension and private pension should establish how each payment will be taxed under the UK–France agreement before making decisions about withdrawals.
What you can do
Contact your pension providers, check the relevant tax treaty and seek regulated pension advice before making significant changes.
YOH Emigration Guide
Planning your move overseas?
Keep the Emigration Guide handy as you work through your plans.
Will you pay tax if you sell or rent out your UK home?
If you're moving abroad permanently, you might be deciding whether to sell your British property or keep it as a rental investment.
Both options can have tax implications.
If you sell your UK home
You may qualify for Private Residence Relief, which can reduce or eliminate Capital Gains Tax when selling your main home.
However, the amount of relief available depends on factors including how long you've owned the property and whether it has been your main residence throughout that period.
If you sell UK property after becoming non-resident, you'll generally need to report the disposal to HMRC within 60 days of completion, even if no tax is due.
Your new country of residence may also have rules governing gains made on overseas property.
If you rent out your UK home
Rental income from a UK property generally remains subject to UK tax, even when you're living abroad.
You may fall under the Non-resident Landlord Scheme, which governs how tax is collected on rental income received by landlords who usually live outside the UK.
Depending on your new country's rules, you may also need to declare the income there.
What you can do
If you're planning to sell or rent out your property, get advice before leaving Britain. The timing of a sale, the availability of tax relief and your future residency status can all affect the outcome.
What taxes will you pay when buying a property abroad?
Alongside your UK tax obligations, you'll need to budget for the taxes associated with purchasing and owning your overseas home.
These vary considerably by country, property type and sometimes region.
| Country | Property taxes to budget for |
|---|---|
| Spain | Property transfer tax on most resale homes or VAT on qualifying new builds, plus applicable stamp duty and annual property tax (IBI). |
| France | Property acquisition taxes and fees, annual taxe foncière and potentially taxe d'habitation on second homes. |
| Portugal | Property transfer tax (IMT), stamp duty and annual municipal property tax (IMI). |
| Greece | Property transfer tax on most resale purchases and annual ENFIA property tax. Different VAT rules may apply to certain new properties. |
| Italy | Registration tax, mortgage and cadastral taxes, or VAT on applicable purchases. Annual IMU property tax may apply, particularly to second homes, alongside the TARI waste tax. |
| Cyprus | Property transfer fees on applicable purchases or VAT on qualifying new properties, plus ongoing municipal and sewerage charges. There is no annual national immovable property tax. |
The amount you pay will depend on your particular purchase. Some countries also have additional taxes relating to wealth, rental income or selling a property.
What you can do
Ask your independent lawyer for a full breakdown of purchase taxes and ongoing ownership costs before committing to a property.
What happens to your savings, investments and inheritance tax?
Moving overseas doesn't mean you have to close all your UK savings accounts or sell your investments. However, their tax treatment may change.
For example, you can generally keep an existing UK ISA after becoming non-resident, but you usually cannot continue paying into it. Although your savings retain their UK tax advantages, your new country may not recognise the ISA's tax-free status.
Inheritance tax is another area worth reviewing, particularly if you own property or investments in more than one country.
Since 6 April 2025, the UK has used a long-term residence-based system to determine whether overseas assets fall within the scope of UK Inheritance Tax.
Broadly, someone who has been UK tax resident for at least ten of the previous 20 tax years may be considered a long-term UK resident. Depending on their residence history, UK Inheritance Tax exposure on overseas assets can continue for several years after departure.
Your destination may also have its own inheritance and succession rules.
What you can do
Review your investments, estate planning and wills with professionals familiar with cross-border arrangements, particularly if you intend to settle overseas permanently.
What if you decide to move back to the UK?
Not every overseas move lasts forever. You might return to Britain to be closer to family, for work or simply because your plans change.
If you become UK tax resident again, you'll normally return to the UK's tax rules for residents.
There's also a provision known as the temporary non-residence rules, which can apply if you return after a relatively short period overseas.
Broadly, if you've previously been UK resident for at least four of the seven tax years before leaving and return after five years or less, certain gains or income received while abroad may become taxable in the UK.
These rules don't apply to all income, and there are specific conditions and exceptions.
What you can do
If there's a possibility you'll return to Britain, discuss this with your tax adviser before selling investments or making large pension withdrawals while overseas.
What should you do before moving abroad?
You don't need to become a tax expert to relocate successfully. But a little preparation can make the financial side of your move much easier to manage.
Start with these five steps:
- Check your tax residency: Establish when you may cease to be UK tax resident and become resident in your new country.
- Tell HMRC you're leaving: Depending on your circumstances, you may need to complete form P85 or the residence pages of your Self Assessment return.
- Review your income: Check how pensions, rental income, employment earnings and investments will be taxed.
- Budget for property taxes: Factor purchase taxes and ongoing ownership costs into your overseas property budget.
- Speak to a cross-border tax specialist: Ideally, do this before moving or making major financial decisions.
You should also consider how exchange rates could affect your property purchase and any regular income transferred overseas. Planning your currency transfers in advance can help you understand the sterling cost of your move.
For support with the wider buying process, speak to an overseas property expert.
Summary
Moving abroad changes your relationship with the UK tax system, but it doesn't necessarily mean paying more tax. Your obligations depend on your residency status, income, assets and destination. By understanding the rules early, checking which reliefs are available and getting the right advice, you can concentrate on the more enjoyable parts of your move.
Frequently asked questions
You may still pay UK tax on certain UK income and gains, including rental income, pensions and gains on UK property. If you're non-UK resident, you generally won't pay UK tax on foreign income, although exceptions and special rules can apply.
Yes, if you're leaving the UK permanently or meet certain other conditions, such as going abroad to work full-time for at least a full tax year. You can notify HMRC using the appropriate form or tax return.
Yes. Countries have different residency tests, so you could qualify as tax resident in both. A double taxation agreement may help determine how your income is taxed and what relief you can claim.
Not necessarily. Some countries have lower tax rates for particular types of income, but others may tax pensions, investments or property differently. The overall outcome depends on your personal circumstances and where you move.
You might also like: