
British retirees can look forward to an increased state pension next year, with their annual payment from the government set to surpass the £13,000 mark. This includes expats claiming their UK pension in Spain.
UK pensions are on track to rise by 3.9% in 2027, making it the sixth consecutive year of hikes above 3%. This is thanks to the UK’s triple lock system, which remains in place until April 20230 and guarantees pensioners an annual uplift pegged to the highest of either CPI inflation, earnings growth or 2.5%. The 2027 triple lock figure for inflation is yet to be finalised but is unlikely to exceed the 3.9% already confirmed for earnings growth.
The expected rise works out at £488 a year and means that from April 2027 pensioners on the full new state pension will pocket £250.70 a week, up from the current £241.30. This equates to £1,086 a month or £13,036 a year. Those on the old basic state pension will receive £192.10 a week (up from £184.90), equal to £768 a month or £9,989 annually.
Download the Spain Buying Guide
Contents
Thinking about moving or buying abroad? Start here
Spend one online day getting practical answers on property, visas, tax, finance and the next steps in your overseas plans.
- 35+ live seminars
- Speak to industry experts
- 30 days of on-demand access
Join at any point during the day.
Get practical answers before you buy or move abroad
Explore upcoming expert-led sessions on property, finance, tax, legal issues, visas and relocation.
How far a UK pension goes in Spain in 2026
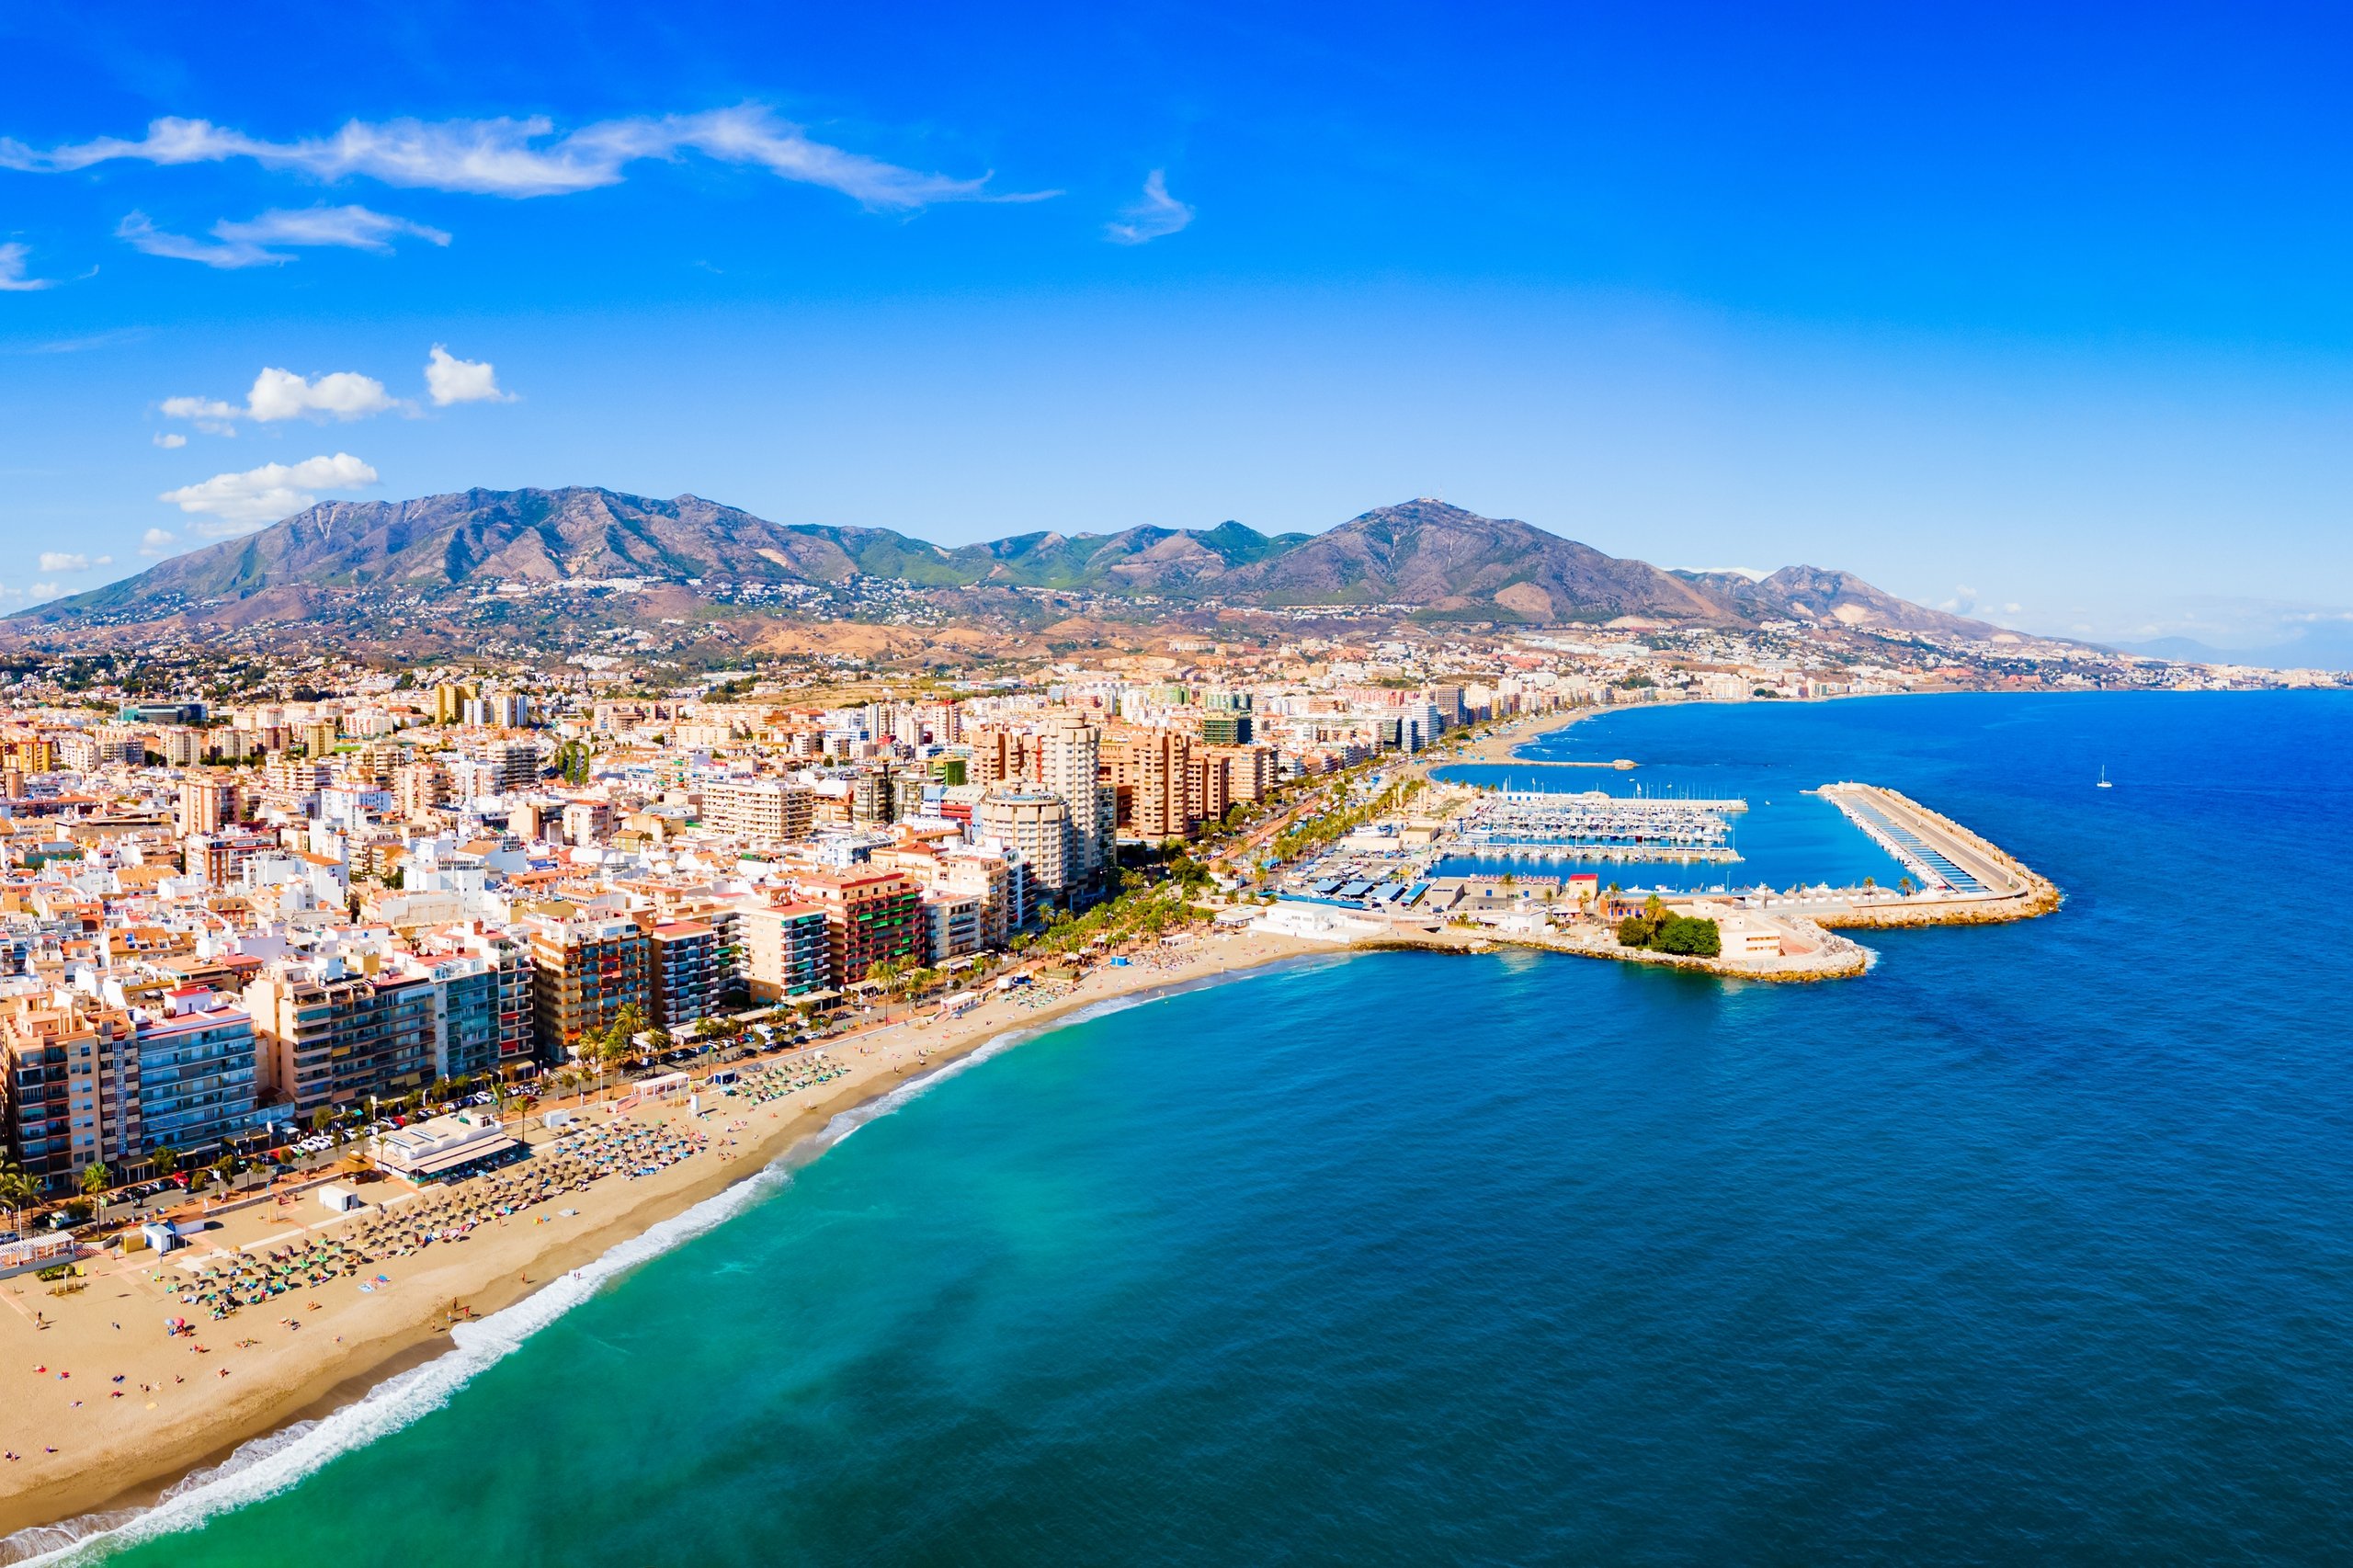
What might this pension boost mean for Brits living in Spain or about to retire there? Without delving too deep, it should make life in the Costas that little bit more affordable than it already is.
According to the Your Overseas Home 2026 Cost of Living Index, an individual can get by adequately in Spain on £833 (€966) a month. This is 32% cheaper than in the UK, where you need £1,218 for a comparable lifestyle.
It makes Spain the best value place to live out of the 12 destinations featured in the Index, ahead of Portugal in second, Italy (third) and Greece (fourth). A total of 50 items or services were compared by YOH, spread across six categories – groceries, running a home, travel and transport, leisure and eating out, personal spending and service, and basic healthcare. Accommodation or property related costs and private medical insurance are excluded.
Based on the results, a monthly pension of £1,086 (€1,260) or €15,122 per year, alone should cover your outgoings comfortably in the Costas, unlike in the UK where it falls short. This is even after it is taxed in Spain, assuming you benefit from Spain's standard tax-free allowance and pension deductions.
An expat whose sole income is a £13,036 (€15,122) UK state pension in Spain should expect to receive €1,110-€1,150 a month after Spanish income tax, depending on age and region (different rules of taxation for certain civil servant pensions).
For a couple in receipt of two UK pensions and sharing living costs, life should be even more affordable. Of course, for some with more expensive lifestyles this won’t be enough while others might live quite happily on less. Even inflation in Europe, expected to ease off across during 2027, can’t spoil the party. Spain’s rate is forecast to trend around 2.5%, meaning expats there should still feel the benefits of a 3.9% pension rise.
Where Spain offers the biggest cost of living savings
Top of the YOH Index, Spain is especially affordable in four areas of day-to-day living – eating out and leisure time, running a home, personal spending and services, and groceries. In fact, it was only more expensive than the UK in one category and only just – basic healthcare, where there was just a £1 difference in the monthly cost!
Spain takes the crown for eating out and leisure
Spain’s real showpiece, eating out and enjoying leisure time, are a big draw for expats. Its £253 monthly spend makes it top of the Index in this category and a hefty 44% cheaper than the UK (£448/month).
No surprises really, when you can still feast on a three-course menu del dia for less than €15 or enjoy a pint for €3 in most Costas. Other things considered in the Index included the cost of a coffee and croissant, Big Mac meal, cinema ticket, Netflix, newspaper, half-marathon entry and video games.
Most affordable European destination for running a home
Expats will be pleased to hear that running a home in the Costas (£169/month) is cheaper than anywhere else European in the Index and 32% less than the UK (£247/month). Only Dubai was marginally less expensive (£161/ month).
This category included items such as maintenance, appliances, phone contracts, electricity and cleaning. With constantly improving building standards and new homes required to be increasingly energy efficient, things are only set to get better in Spain.
Good value for groceries and personal spending
Scoring highly for personal spending and services, a monthly budget of £57 makes Spain 32% cheaper than the UK (£84) and third in this category overall. Outgoings measured included clothes, haircuts and dog-grooming.
Spain is fourth in the groceries category, but in truth there’s barely anything between the top four spots. According to the Index, a monthly food shop in Spain (£167) is only £6 more expensive than in Greece, the best value destination. Compared to the UK (£215/month), it’s a significant 22% cheaper. The weekly markets and huge supermarkets you find all along the Costas make feeding yourself affordable and fun in Spain!
Other considerations when you move to Spain
A monthly budget of £833 (€966) is a useful guide to regular living costs in Spain. The YOH Index does not take into account the costs that come with buying and owning a new home there. Your monthly spend would need to be calculated after any mortgage or rent payments. Also not included is the cost of private healthcare.
Other expenses that fall outside the Index could relate to your specific home, such as a swimming pool to maintain or community fees (if you live on a desirable golf resort or somewhere with lots of amenities these can be high). All of which means, just how far a pension of £13,036 a year will go will depend very much on your personal lifestyle.
Could your UK state pension in Spain get you Spanish residency?
Most retirees and semi-retirees who want to live in Spain without working apply for the non-lucrative visa (NLV). A key requirement is proof you have sufficient means to cover the day-to-day costs of living in the country – and a UK state pension can count towards this. After your first year, you need to renew and prove financial means for another two years, followed by a further two years. After five years you can obtain permanent residency and no longer need to prove your income.
For UK and other non-EU citizens, how much income you receive annually is also critical to helping you move to Spain permanently. The NLV doesn't allow you to work once there, so most applicants rely on pensions, savings or passive income.
In 2026, the minimum amount of monthly income required for an NLV applicant is €2,400, equivalent to 400% of Spain's Public Multiple Effects Income Indicator (IPREM). Alternatively, applicants can show financial assets or savings amounting to the annual requirement of €28,800. Adding a spouse or qualifying family member to your application adds another €600/month or €7,200/year per person.
This means a couple need a combined income of €3,000 a month (€36,000 a year). A husband and wife each receiving the potential £13,036 (€15,122) a year state pension, so combined total of €30,244, aren’t a million miles off meeting these requirements.
For most British retirees, combining their state pension income with cash in the bank or combination of an occupational pension, drawdown from a private pension, income from an annuity is enough to obtain an NLV.
Exchange rate effect on your Spanish income
As a final takeaway, don’t ignore the effect the exchange rate could have on your monthly UK state pension in Spain. Any UK-sourced payments coming from pensions or other type of investment will need to be transferred into euros before it hits your Spanish bank account.
This leaves your income exposed to exchange rate movement, as well as expensive receiving fees from Spanish banks. A UK state pension payment of £1,086 could be worth €1,260 one month, based on a £1/€1.16 exchange rate. If the rate drops to £1/€1.15 the following month, your income in Spain falls by €11. Scale up the amount you transfer from the UK each month and the potential difference in the amount of euros hitting your Spanish account increases too.
The solution to protecting your money from this uncertainty, guaranteeing competitive exchange rates and minimising bank charges is to use YOH’s currency transfer partner Smart Currency Exchange. They have clever ways of fixing your monthly euro payments in Spain, by combining a forward contract with their regular payment plan tool.
Exchange rate applied: £1/€1.16
Note, information in this article is provided for general informational purposes only and does not constitute formal advice. Always seek professional advice before making decisions relating to financial and estate planning, inheritance and other related matters.